
What Role Does Securities Lending Play in Market Liquidity?
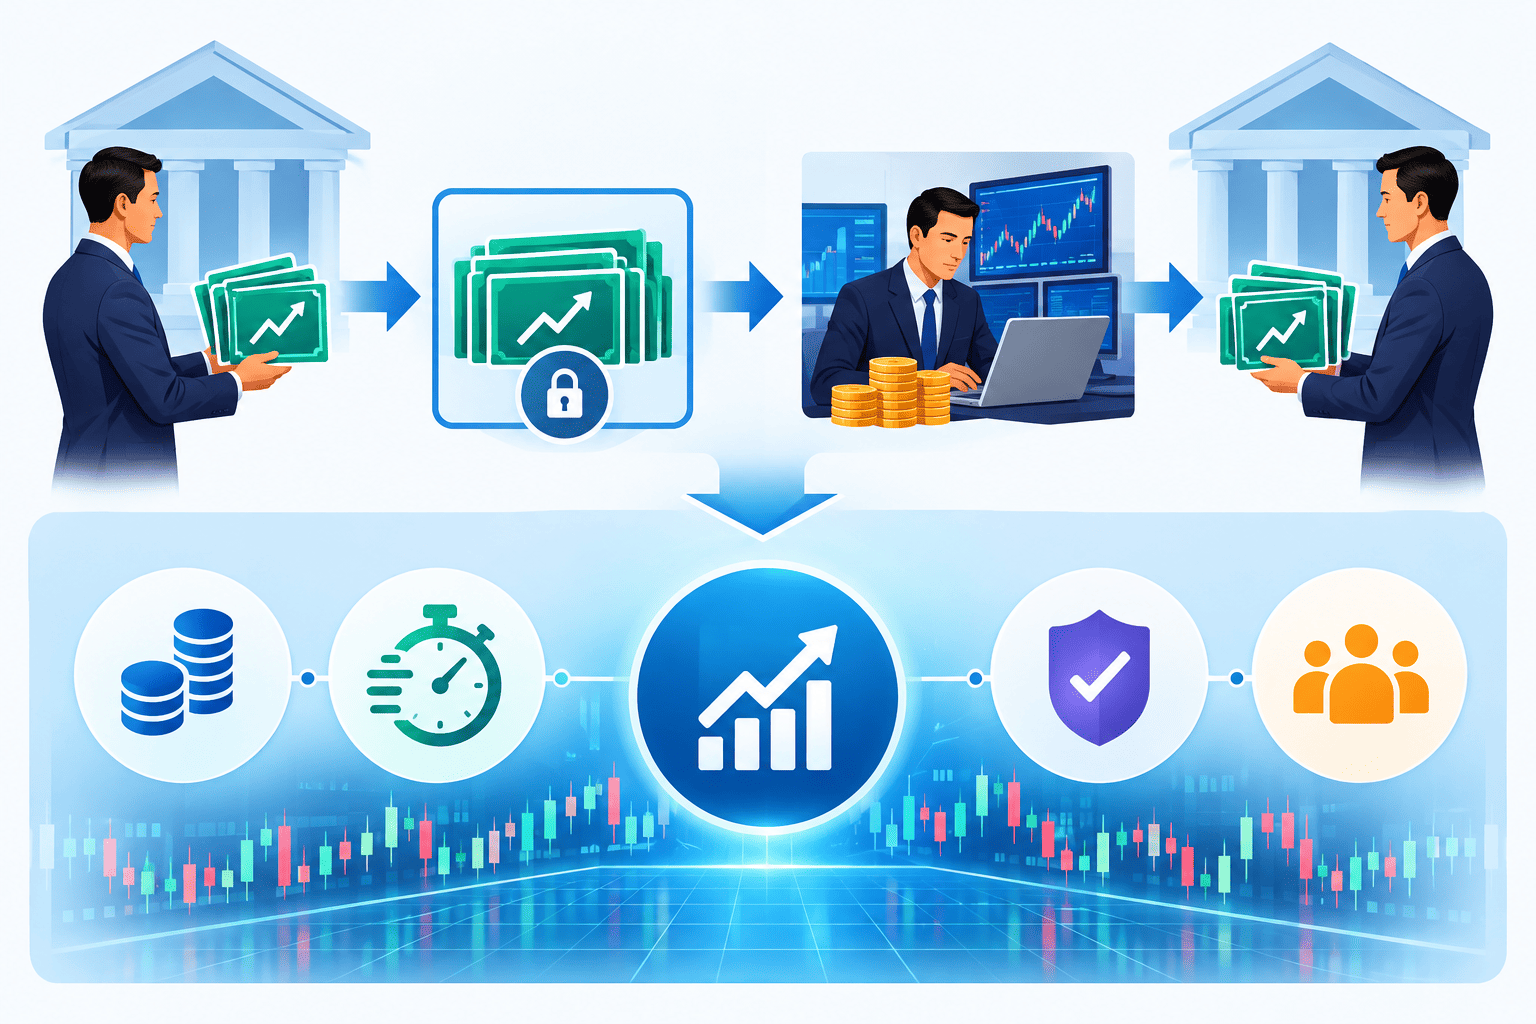
Securities lending is a foundational mechanism in modern capital markets. It allows institutional owners of stocks, bonds, and other securities to temporarily transfer those assets to borrowers in exchange for collateral and a fee. The practice does far more than generate incremental income for lenders. It expands the effective supply of securities available for trading, short selling, market making, settlement, and arbitrage. In doing so, it directly supports market liquidity, tighter spreads, more accurate price discovery, and overall market resilience.
As of late 2025 and into 2026, the scale of this activity underscores its systemic importance. Global securities lending revenues reached record levels near $15 billion in 2025, with loan balances exceeding $4 trillion for the first time. Lendable assets stood at approximately $48.5 trillion by year-end 2025, according to industry data. Activity has remained elevated in 2026, with first-half revenues around $9.1 billion and average balances climbing further. These figures reflect sustained demand driven by volatility, thematic trades such as artificial intelligence-related equities, mergers and acquisitions, and shifts in monetary policy.
How Securities Lending Works
In a typical transaction, a beneficial owner (pension fund, mutual fund, insurance company, or endowment) authorizes a lending agent to lend securities from its portfolio. The borrower, often a hedge fund, broker-dealer, or market maker, posts collateral (cash or high-quality securities) that exceeds the value of the borrowed securities. The borrower pays a fee based on demand and scarcity. The lender can reinvest cash collateral for additional return, subject to risk controls.
Loans are usually open-ended or short-term and can be recalled if the lender needs the securities back for voting or sale. Strict collateralization, daily marking to market, and indemnification practices by agents help manage counterparty risk. This structure has evolved into a highly standardized, technology-supported market that operates across equities, government bonds, corporate bonds, and exchange-traded products.
By mobilizing idle securities held by long-term investors, the process increases the float available for active market participants without forcing permanent sales.
Direct Contributions to Market Liquidity
Market liquidity depends on the ability of buyers and sellers to transact quickly at prices close to prevailing market levels with minimal price impact. Securities lending enhances this in several concrete ways.
First, it enables short selling. Short sellers borrow securities and sell them in the open market, providing downward pressure that helps correct overvaluations and improves price discovery. Without ready access to borrowable shares or bonds, short interest would be constrained, potentially leading to more one-sided markets and larger price dislocations. Empirical observations and regulatory commentary consistently note that securities lending expands the supply available for these activities and thereby supports more efficient pricing.
Second, it supports market makers and dealers. Broker-dealers frequently need to borrow securities to fulfill client orders, hedge inventory, or maintain continuous two-way quotes. Access to a deep lending pool reduces the risk of failed settlements and allows dealers to intermediate more effectively. This is especially visible in less liquid names or during periods of elevated volatility, when the ability to locate and borrow securities quickly preserves trading continuity.
Third, it facilitates settlement and reduces fails. In markets with compressed settlement cycles (such as the move toward T+1 in various jurisdictions), the ability to borrow securities on short notice helps cover temporary shortages and keeps the settlement system functioning smoothly. Regulatory and industry bodies have long recognized this role in maintaining orderly markets.
Fourth, it underpins arbitrage and relative-value strategies. These strategies keep prices aligned across related instruments (for example, cash equities versus futures or ETFs versus underlying baskets). When arbitrageurs can borrow the necessary securities efficiently, mispricings are corrected faster, which benefits all market participants through tighter and more consistent pricing.
Collectively, these functions increase the effective supply of tradable securities, lower search costs for borrowers, and reduce the likelihood of liquidity dry-ups in stressed conditions. Industry analyses, including those from bodies focused on securities finance, emphasize that securities lending improves market liquidity and enhances price discovery by making more securities available for trading and related activities.
Recent Market Scale and Trends (2025–2026)
The importance of securities lending is reflected in its recent growth. In 2025, global revenues hit record highs of approximately $14.9 billion to $15.3 billion, representing increases of 26–27 percent year-over-year depending on the data provider. Equities drove much of the expansion, particularly in Asia where AI and semiconductor themes fueled strong borrowing demand. Exchange-traded products and American Depositary Receipts also posted outsized gains. Average on-loan balances crossed $4 trillion, while lendable assets reached the high $40 trillion range and continued expanding.
Into 2026, momentum has persisted. First-half revenues approached $9.1 billion, up more than 30 percent from the prior year, with average loan balances rising further amid geopolitical uncertainty, rate path debates, and continued thematic trading. Asian equities, certain technology names, and ETFs have remained key contributors. Lendable inventory has grown in line with rising market valuations and broader institutional participation in lending programs. Utilization rates and fee dynamics vary by asset class and region, but the overall picture is one of a larger, more active market supporting higher volumes of underlying trading and hedging activity.
These figures illustrate that securities lending is not a peripheral activity. It operates at a multi-trillion-dollar scale and generates substantial revenues while serving as infrastructure for the broader equity and fixed-income markets.
Benefits Across Market Participants
Lenders earn additional income that can enhance portfolio returns for the ultimate beneficiaries (pensioners, policyholders, or fund investors). Borrowers gain the ability to express views, hedge risks, or fulfill obligations that would otherwise be difficult or more expensive. Market makers and intermediaries operate with greater flexibility. End investors benefit indirectly through improved secondary-market liquidity and more reliable pricing in the instruments they hold or trade.
For exchange-traded funds specifically, securities lending supports both revenue generation that can offset expenses and the arbitrage mechanisms that keep ETF shares trading close to net asset value. As ETF assets have grown substantially, the associated lending activity has become an important part of the ecosystem.
Risks and Mitigants
No market mechanism is risk-free. Securities lending involves counterparty risk, collateral risk (especially when cash is reinvested), operational risk around recalls, and potential conflicts around voting rights. These are managed through over-collateralization, daily valuation, diversification of reinvestment, indemnification by agents in many programs, and clear contractual frameworks such as the Global Master Securities Lending Agreement.
Regulators and industry associations continue to monitor the market for systemic implications, particularly around concentrated borrowing or collateral practices. The overall track record, however, shows that well-structured programs have operated through multiple market cycles while supporting liquidity rather than impairing it.
Comparison of Liquidity Support Mechanisms
The following table provides a concise comparison of how securities lending contributes to liquidity relative to other common market features:
| Mechanism | Primary Function | Impact on Available Supply | Typical Time Horizon | Key Beneficiaries | Sensitivity to Volatility |
| Securities Lending | Temporary transfer of ownership rights | Directly increases borrowable float | Days to months | Short sellers, market makers, arbitrageurs | High demand often rises |
| Market Making | Continuous two-way quoting | Indirect via inventory | Intraday | All traders | High |
| Repo Markets | Short-term financing against collateral | Supports dealer balance sheets | Overnight to term | Dealers, leveraged investors | High |
| Central Bank Facilities | Emergency liquidity or collateral access | Targeted in stress | Discretionary | Systemically important firms | Activated in crises |
| ETF Creation/Redemption | Arbitrage around NAV | Indirect via underlying | Daily | ETF investors and APs | Moderate to high |
Securities lending stands out for its direct expansion of the tradable and borrowable supply of specific securities on a scalable, market-driven basis.
Looking Ahead
Structural trends point to continued relevance. Expanding passive ownership creates large pools of lendable assets. Growth in ETFs, options activity, and cross-border investing sustains borrowing demand. Regulatory moves toward shorter settlement cycles increase the value of rapid access to securities. Technology platforms are improving transparency, automation, and the matching of supply with demand, which should further support efficiency.
At the same time, participants must navigate fee compression in general collateral markets, evolving collateral preferences, and the need for robust risk management. The core function remains intact: securities lending acts as a flexible inventory management and liquidity provision tool for the global capital markets.
For further authoritative information on market structure and practices, readers can consult resources from the International Securities Lending Association and detailed industry data and analysis available through S&P Global Market Intelligence securities finance reports.
In summary, securities lending plays a critical enabling role in market liquidity. By unlocking securities held by long-term investors and making them available to those who need them for trading, hedging, and settlement, it reduces frictions, supports continuous two-sided markets, and contributes to more resilient price formation. The record activity levels of 2025 and the strong continuation into 2026 demonstrate that this function remains vital amid evolving market conditions.
Frequently Asked Questions
1. Do the 2023 US Merger Guidelines still apply under the current administration?
2. How long does a typical multi-jurisdictional merger review take?
3. Are private equity roll-up strategies still viable?
4. What types of remedies do agencies prefer today?
Last Updated on 25 September, 2026
By entering the email address you agree to our Privacy Policy.