
Earn-Outs and Deferred Consideration in Indian M&A: Bridging the Valuation Gap Without Buying a Dispute
Introduction
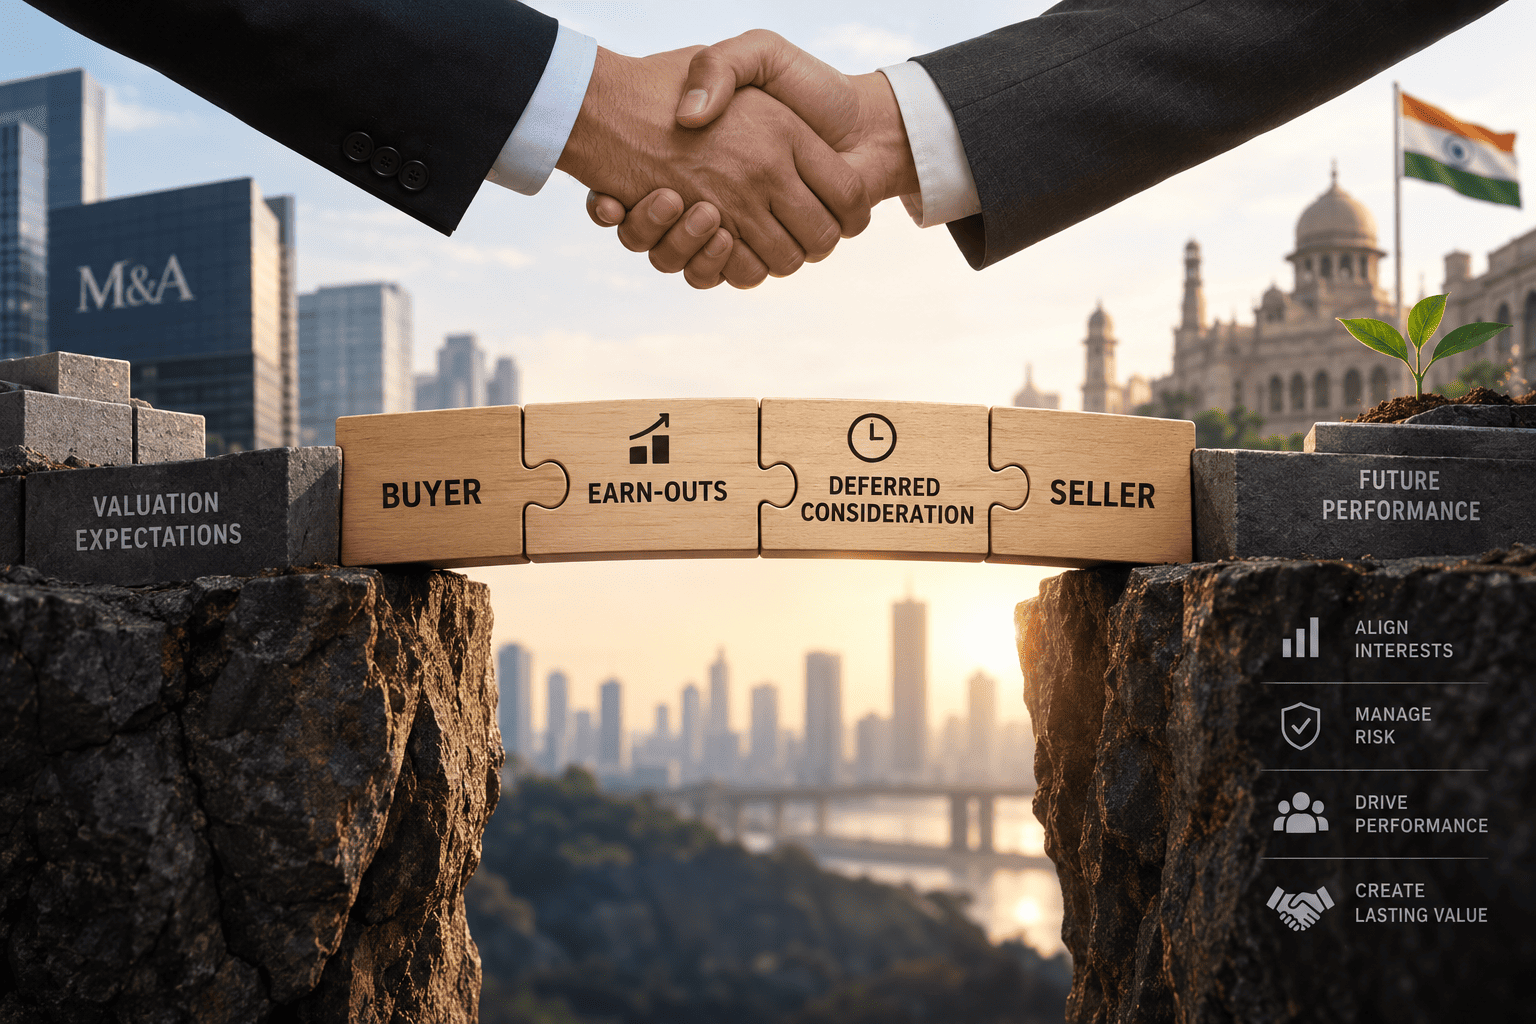
Every deal team eventually runs into the same conversation: the seller believes the business is worth what it will become, and the buyer is only willing to pay for what it can already see in the numbers. An earn-out paying part of the consideration later, contingent on the target hitting agreed performance milestones is a standard tool for closing that gap without either side simply walking away. It is used in Indian M&A, particularly in founder-led and startup acquisitions where historical financials may understate future potential.
But an earn-out that is not carefully built does not close the valuation gap so much as postpone the argument about it. Indian deal teams also have a specific regulatory and tax landscape to navigate, meaning that a template Delaware-style earn-out clause may not adequately address an Indian transaction. This article sets out why earn-outs are used, the key regulatory and tax considerations that may apply, and where the drafting effort should concentrate.
Why Buyers and Sellers Reach for Earn-Outs
An earn-out is fundamentally a risk-allocation device. Instead of pricing the target on a single agreed valuation, the parties agree on an upfront payment reflecting what both sides are confident about, and a further, contingent payment tied to the target’s performance against revenue, EBITDA, customer retention, or similar metrics over an agreed period after closing.
It lets a seller who is convinced of the business’s trajectory capture that upside without demanding that the buyer pay for it today, and it lets a buyer who is unwilling to underwrite an optimistic forecast defer that portion of the price until the forecast either materialises or does not. Earn-outs can be particularly relevant in transactions involving technology, consumer and other high-growth businesses where valuation expectations may differ significantly between the parties. They can also help facilitate transactions where the buyer and seller have different views on the reliability of future projections.
Earn-outs also serve a retention purpose that is easy to overlook. Where the seller’s founders or key managers are staying on to run the business, tying part of the consideration to post-closing performance gives them a direct financial incentive to deliver the results the buyer paid for. This is one reason earn-out structures are particularly common in founder-led acquisitions, as opposed to financial sponsor-to-financial sponsor deals where no individual seller remains involved after closing.
The Regulatory and Tax Framework for Deferred Consideration
Where a transaction involves a non-resident buyer or seller, deferred consideration does not operate in a purely contractual vacuum; it sits within India’s foreign exchange framework.1
Rule 9(6) of the Foreign Exchange Management (Non-Debt Instruments) Rules, 2019 permits, in a transfer of equity instruments between a person resident in India and a person resident outside India, an amount not exceeding 25% of the total consideration to be paid on a deferred basis within a period not exceeding 18 months from the date of the transfer agreement. The rules also permit the relevant amount to be dealt with through an escrow arrangement, or through an indemnity structure in the circumstances specified under the Rules.
The Reserve Bank of India’s Master Direction on Foreign Investment in India was updated in January 2025 to clarify that arrangements permitted under the NDI Rules for direct foreign investment, including deferred payment arrangements and escrow structures, are also available for downstream investments by foreign-owned or foreign-controlled Indian entities, subject to the applicable conditions.
Accordingly, where an earn-out or other deferred consideration mechanism is used in a cross-border transaction involving Indian equity instruments, the structure should be tested against the applicable FEMA and NDI Rules requirements at the drafting stage. The 25% and 18-month parameters should not be treated as merely commercial terms; they can have direct regulatory significance.
Taxation is the second, and more complex, part of the analysis. The Income-tax Act, 1961 does not contain a standalone regime specifically governing earn-outs. The tax treatment of contingent or deferred consideration has therefore been shaped in part by judicial decisions and depends significantly on the precise terms and circumstances of the transaction. In CIT v. Mrs. Hemal Raju Shete2, the Bombay High Court considered deferred consideration linked to the future profits of the business. It held, on the facts of that case, that the contingent deferred consideration had not accrued where the seller did not have a legally enforceable right to receive a particular amount at the time of transfer.
The Delhi High Court took a different approach in Ajay Guliya v. ACIT3, where the deferred amount formed part of the agreed consideration for the shares and the court upheld taxation of the consideration in the year of transfer. The decision placed emphasis on the statutory scheme under Section 45(1) and the fact that the transfer of the shares had already taken place.
The apparent divergence demonstrates why the drafting and tax characterisation of an earn-out matter. The precise distinction between an ascertainable deferred payment and genuinely contingent consideration, the conditions attached to payment, and the seller’s enforceable rights can materially affect the tax analysis. Tax counsel should therefore review the structure before the transaction documents are finalised rather than treating the earn-out as a purely commercial provision.
Why Earn-Out Disputes Are a Growing Concern in Indian Dealmaking
Earn-out disputes arise for reasons that are structural rather than merely incidental. The metrics used to measure earn-out performance are frequently softer than they appear on paper. “EBITDA” and “revenue”, for example, depend on accounting policies and business decisions that a buyer, now in control of the target, may influence after closing through changes in cost allocation, investment decisions, integration or other operational measures.
Sellers, meanwhile, often have limited visibility into the target’s post-closing operations once they have handed over control. This can make it difficult to assess whether the business has been operated consistently with the assumptions underlying the earn-out.
Because these disputes can turn on detailed commercial, accounting and contractual questions, transaction documents increasingly use a combination of expert determination and arbitration to deal with different categories of disagreement. Expert determination can be particularly suitable for a narrow accounting dispute, while arbitration may be more appropriate where the dispute involves contractual interpretation, alleged breach of post-closing covenants or other legal questions.
The result is that a poorly drafted earn-out can generate a post-closing dispute that is expensive and difficult to resolve, often over matters that could have been addressed more precisely when the transaction documents were negotiated.
Special Focus Areas When Drafting the Earn-Out Clause
Five areas deserve particular drafting attention.
First, the performance metric itself should be defined with enough precision to be independently auditable. A bare reference to “EBITDA” invites exactly the kind of post-closing disputes that earn-outs are prone to generate. A better approach is to identify the accounting principles to be applied, prescribe how specific items are to be treated, and establish a process for preparing and reviewing the earn-out calculation. Where appropriate, the agreement should provide for determination by an independent accountant and specify the scope of that determination.
Second, the agreement should address the buyer’s post-closing conduct. Depending on the commercial arrangement, this may include an obligation to operate the target in the ordinary course, maintain agreed accounting policies, or refrain from taking actions specifically designed to frustrate the achievement of the earn-out. The parties should also consider how material changes in accounting methodology, business integration, transfer of business opportunities or changes affecting key customers may impact the earn-out calculation.
The objective should not necessarily be to prevent the buyer from making legitimate business decisions, but to ensure that the agreed mechanism for measuring the seller’s contingent consideration is not rendered meaningless by post-closing conduct.
Third, sellers should scrutinise any set-off right the buyer reserves against the earn-out for indemnity claims. An unrestricted set-off can allow the buyer to withhold an earn-out on the basis of an unresolved or unquantified claim. A seller-friendly position would limit set-off to claims that are agreed in writing or have been finally determined through the agreed dispute-resolution mechanism, subject to the commercial position negotiated between the parties.
Fourth, the choice between expert determination and arbitration for resolving earn-out disagreements should be made deliberately rather than by default. Expert determination is generally better suited to a narrow accounting or calculation dispute, while arbitration may be more appropriate where the disagreement raises genuine questions of contractual interpretation or breach of the wider transaction documents. The agreement should also clearly identify which issues fall within each mechanism to avoid a preliminary dispute about the appropriate forum.
Fifth, tax and FEMA counsel should be involved at the drafting stage. The tax consequences may differ depending on whether the payment is structured as contingent purchase consideration, an employment-linked payment or a payment for services. In addition, where the transaction involves a non-resident, the deferred consideration mechanism must be tested against the applicable FEMA and NDI Rules requirements. The characterisation of the payment should therefore be considered alongside, and not after, the commercial drafting.
Conclusion
An earn-out is a genuinely useful way to close a valuation gap that would otherwise kill a deal, but it only works if it is drafted as a self-contained mechanism capable of addressing the disputes it is likely to generate: a precise metric, clear treatment of the buyer’s post-closing conduct, a considered set-off position, an appropriate dispute-resolution mechanism, and tax and FEMA structuring done upfront rather than as an afterthought.
Parties that treat the earn-out clause as boilerplate rarely save time by doing so. They simply move the argument about the company’s value from the negotiating table to a post-closing dispute, potentially with legal and expert costs added on top. In Indian M&A, the better approach is to treat the earn-out not merely as a pricing mechanism, but as a carefully engineered part of the transaction architecture.
- Foreign Exchange Management (Non-Debt Instruments) Rules 2019, r 9(6); Reserve Bank of India, Master Directions https://www.rbi.org.in/Scripts/BS_ViewMasDirections.aspx?id=11200. ↩︎
- Commissioner of Income Tax v Mrs Hemal Raju Shete (2016) 239 Taxman 176 (Bom), ITA No 2348 of 2013. ↩︎
- Ajay Guliya v Assistant Commissioner of Income Tax [2012] 276 (Del), ITA No 423/2012. ↩︎
Frequently Asked Questions
1. What is an earn-out in an Indian M&A deal?
2. Is there a cap on deferred consideration in cross-border M&A transactions in India?
3. How is deferred consideration taxed in India?
4. Why do earn-out clauses lead to disputes after closing?
Last Updated on 17 September, 2026
By entering the email address you agree to our Privacy Policy.